
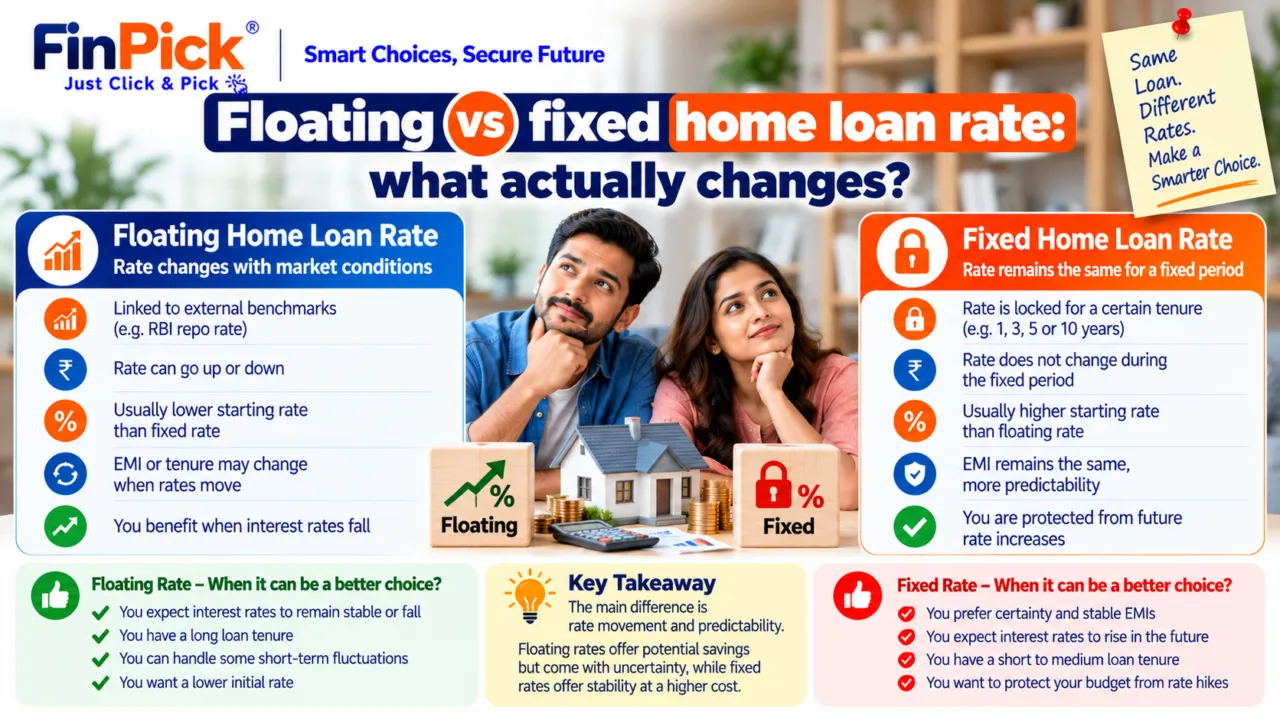
You open your bank app one morning and see a notification: “Your home loan EMI has changed.” The repo rate moved last week, and now your ₹43,390 monthly payment is ₹42,600. You saved ₹790 a month without doing anything. Six months later, the repo rate rises, and the EMI climbs back up. If you took a floating-rate home loan after October 2019, this is how it works now, and you have more control than you think.
Since 1 October 2019, the Reserve Bank of India requires banks to link new floating-rate housing, auto and MSME loans to an external benchmark, usually the repo rate. Your loan rate resets at least once every three months when the benchmark moves. The bank sets a spread on top of the benchmark, and RBI limits when that spread can change: the credit-risk premium part only if your credit profile changes substantially, and the operating-cost part only once in three years. From August 2023, at every reset, your lender must offer you a choice: switch to a fixed rate, raise your EMI, extend your loan tenure or prepay part or all of the loan. From January 2026, prepaying a floating-rate loan to an individual for non-business purposes carries no charge at all.
What Happened
Before October 2019, most floating-rate home loans were linked to the bank’s own Marginal Cost of Funds based Lending Rate (MCLR), which could take months to reflect a repo rate change. RBI’s 2019 rule forced banks to link new loans to an external benchmark, making rate changes faster and more transparent. In August 2023, RBI went further: at each reset, you must be offered four options, not just a silent EMI change. And in July 2025, RBI issued directions (effective 1 January 2026) removing prepayment charges on floating-rate loans to individuals for non-business purposes.
Key Facts
- 1 October 2019: RBI requires banks to link new floating-rate housing, auto and MSME loans to an external benchmark such as the repo rate, a 3-month or 6-month Treasury bill, or an FBIL benchmark. Most banks chose the repo rate.
- Reset frequency: At least once every three months.
- Spread rules: The bank sets a spread over the benchmark. The credit-risk premium part can change only if your credit assessment changes substantially. The operating-cost part can change only once in three years.
- Older MCLR loans: Continue under old rules until repayment or renewal. You may opt to migrate to the external benchmark, possibly paying a fee.
- 18 August 2023: RBI circular requiring lenders to offer a choice at reset: switch to fixed rate under the bank’s board policy, raise EMI, extend tenure or prepay (part or full). Lenders had to comply by 31 December 2023.
- Switching charges: Must be disclosed in your sanction letter and again if revised.
- Tenure extension limit: Must not cause negative amortisation. Your EMI must cover at least the monthly interest.
- Quarterly statements: Lenders must send statements showing principal and interest recovered, EMI, EMIs remaining and annualised rate. You must be told of any EMI or tenure change.
- 1 January 2026: No prepayment charges on floating-rate loans to individuals for non-business purposes. Fixed-rate loans may still carry prepayment charges. Undisclosed charges cannot be recovered.
- 2023 rates (dated): Fixed-rate home loans were quoted near 14 percent versus 9 to 9.40 percent floating at major banks.
- August 2026 draft proposal (subject to consultation ending 11 September 2026): Separate benchmark and spread disclosure, effective 1 April 2027. Existing borrower migration by 1 April 2029 with consent and no charge. This is a draft and may change.
Why It Matters
Before 2019, a repo rate cut could take six months to show up in your EMI, if it showed up at all. Now, if the repo rate falls by 25 basis points, your loan rate falls by 25 basis points within three months. The same happens in reverse when rates rise. You see the benefit (or the cost) almost immediately.
The August 2023 rule matters even more: you are no longer a passive recipient of rate changes. At every reset, you can choose to lock in a fixed rate if you expect rates to rise, or extend your tenure to keep your EMI steady, or prepay a chunk to cut your total interest. The bank must offer all four options and disclose any switching charges upfront.
And from January 2026, prepaying a floating-rate loan is free. If you get a bonus or sell an asset, you can throw that money at your loan without penalty, cutting years off your repayment and lakhs off your interest.
How It Actually Works
Here is the mechanism, step by step:
- The benchmark moves: The RBI changes the repo rate (or the Treasury bill rate, if that is your benchmark). Your loan rate is benchmark plus spread.
- The reset date arrives: Your loan resets at least once every three months. On that date, your new rate is the current benchmark plus your spread.
- The bank calculates: If the rate has changed, the bank calculates what happens to your EMI or tenure if nothing else changes.
- You receive four options: The bank must offer you: (a) switch to a fixed rate under the bank’s board policy, (b) raise your EMI to keep the tenure the same, (c) extend your tenure to keep the EMI the same (as long as the EMI still covers the monthly interest), or (d) prepay part or all of the loan.
- You choose: If you do nothing, the bank applies its default (usually raising the EMI or extending the tenure, depending on the bank’s policy). If you choose, you tell the bank which option you want. Any switching charges must have been disclosed in your sanction letter.
- The change takes effect: Your new EMI or tenure starts from the next billing cycle.
The spread itself can change, but only under strict RBI limits. The credit-risk premium part can change only if your credit profile changes substantially (for example, you default on another loan, or your credit score drops sharply). The operating-cost part can change only once in three years. The bank cannot raise the spread just because it feels like it.
Who Is Affected
Floating-rate home loan borrowers (loans taken after 1 October 2019): You see your EMI or tenure change at least every three months when the repo rate moves. From August 2023, you can choose what happens at each reset. From January 2026, prepaying costs nothing.
Older MCLR borrowers (loans taken before 1 October 2019): Your loan still resets on the old MCLR schedule. You can ask your bank to migrate to the external benchmark, but the bank may charge a switching fee. Calculate whether the faster resets and the 2026 prepayment benefit are worth the fee.
Fixed-rate home loan borrowers: Your EMI never changes, no matter what the repo rate does. You pay a higher initial rate (in 2023, near 14 percent versus 9 to 9.40 percent floating), and prepayment may still carry a charge even after January 2026. You are unaffected by the reset rules.
MSME borrowers: The October 2019 external benchmark rule covers MSME loans too, so the same reset and spread rules apply. Business loans for non-personal purposes may still carry prepayment charges even if floating-rate.
A Worked Example
This is an illustration, not a projection. Suppose you have a ₹50 lakh home loan at 8.5 percent for 20 years. Your EMI is about ₹43,390 a month.
The repo rate falls by 25 basis points (0.25 percent). At the next reset, your loan rate becomes 8.25 percent. Your new EMI, if you keep the tenure at 20 years, is about ₹42,600. You save ₹790 a month, or ₹9,480 a year.
Now the bank offers you four options:
- Raise EMI: Keep the tenure at 20 years. Your EMI becomes ₹42,600. You finish the loan on schedule and save ₹9,480 every year for the remaining tenure.
- Extend tenure: Keep the EMI at ₹43,390. The bank calculates a new tenure (slightly shorter than 20 years, because the rate fell). You pay the same amount each month, but you finish earlier and save on total interest.
- Switch to fixed: Lock in a fixed rate (say, 9 percent, if that is the bank’s fixed-rate offer). Your EMI becomes about ₹44,990. You pay more now, but you are protected if rates rise later. The bank may charge a switching fee.
- Prepay: Use a bonus or savings to pay off ₹5 lakh. Your outstanding balance becomes ₹45 lakh. At 8.25 percent for the remaining tenure, your EMI drops to about ₹38,340. You save ₹5,050 a month and cut years off your loan. From January 2026, this costs nothing.
The arithmetic works in reverse if the rate rises. A 25 basis point rise takes your EMI from ₹43,390 to about ₹44,180, costing you ₹790 a month. You can choose to extend the tenure to keep the EMI steady, or prepay to bring it back down.
FinPick Analysis
This is FinPick’s reading, not reported fact.
The 2019 and 2023 rules are a quiet revolution. For the first time, a home loan borrower in India has real control at every rate change, not just at the start. The problem is that most banks show you only the new EMI. They do not show you the total interest saved or paid over the life of the loan if you raise the EMI versus extending the tenure, or the five-year cost of switching to fixed versus staying floating.
FinPick’s view: the right choice depends on three things. One, your cash flow: can you afford a higher EMI if rates rise, or do you need the safety of a fixed rate or extended tenure? Two, your rate outlook: if you think rates will rise, switching to fixed or prepaying now saves you money. If you think rates will fall, stay floating. Three, your remaining tenure: if you have 15 years left, a small EMI change compounds into lakhs of rupees of interest. If you have 3 years left, the difference is smaller.
The January 2026 prepayment rule is the biggest gift. Every rupee you prepay on a floating-rate loan saves you 8 to 9 percent a year (your loan rate) with zero risk and zero charge. That is better than most fixed deposits and as good as many equity mutual funds on a risk-adjusted basis. If you have a floating-rate loan and a lump sum, prepaying is almost always the right first move.
The draft 2026 rules (separate benchmark and spread disclosure, migration by April 2029) are still under consultation. If they go through, you will see exactly how much of your rate is benchmark and how much is spread, making it easier to compare banks and negotiate. But those rules are not final yet.
What You Should Know Before You Act
Check your loan type: If your loan was taken after 1 October 2019, it is almost certainly linked to an external benchmark (usually repo). If it was taken before, it is probably MCLR. Your sanction letter or loan statement will say.
Know your reset date: Your loan resets at least once every three months, but the exact date depends on your bank’s policy. Check your quarterly statement or ask your bank.
Read the switching charges: If you want to switch to fixed rate or migrate from MCLR to external benchmark, the bank may charge a fee. It must have been disclosed in your sanction letter. Ask for the current fee before you decide.
Do the full-tenure arithmetic: A lower EMI sounds good, but if you extend the tenure, you may pay more total interest. A higher EMI sounds painful, but if you keep the tenure, you finish earlier and save lakhs. Use a loan calculator or ask FinPick to model both options with your actual numbers.
Prepay if you can: From January 2026, prepaying a floating-rate loan is free. If you have a bonus, a maturity, or savings sitting in a low-interest account, prepaying cuts your loan faster than almost any other use of that money.
Fixed is not always safer: A fixed rate protects you from rate rises, but you pay a premium upfront (in 2023, about 4 to 5 percentage points more than floating). If rates fall, you are stuck. Fixed makes sense only if you are very sure rates will rise and you cannot afford the EMI increase.
Frequently Asked Questions
Q: If the repo rate falls, does my EMI fall immediately? A: Not immediately. Your loan resets at least once every three months. On your reset date, the new rate applies. If the repo rate fell after your last reset, you will see the benefit at the next reset.
Q: Can the bank raise my spread whenever it wants? A: No. The credit-risk premium part of the spread can change only if your credit profile changes substantially (for example, a default or a sharp credit score drop). The operating-cost part can change only once in three years. The bank cannot raise the spread just because the repo rate fell.
Q: What happens if I do nothing when the rate changes? A: The bank applies its default policy, usually raising your EMI or extending your tenure. You should receive a notification and a quarterly statement showing the change. If you want a different option (switch to fixed, prepay, etc.), you must tell the bank.
Q: Is switching to a fixed rate free? A: Not necessarily. The bank may charge a switching fee. It must have been disclosed in your sanction letter and again if revised. Ask your bank for the current fee before you switch.
Q: Can I prepay my floating-rate loan without penalty right now? A: From 1 January 2026, yes, if the loan is to an individual for non-business purposes. Before that date, the bank may charge a prepayment penalty. Check your sanction letter or ask your bank.
Q: Should I migrate my old MCLR loan to the external benchmark? A: It depends. The external benchmark resets faster, so you benefit sooner when rates fall. But the bank may charge a migration fee. Calculate whether the faster resets and the 2026 prepayment benefit are worth the fee over your remaining tenure. FinPick can model this for you with your actual loan balance and tenure.
Conclusion
Floating versus fixed is not a one-time choice anymore. Since October 2019, your floating-rate home loan resets at least every three months, and since August 2023, you can choose what happens next: raise EMI, extend tenure, switch to fixed or prepay. From January 2026, prepaying a floating-rate loan is free, making it one of the safest and highest-returning uses of a lump sum.
The right choice depends on your cash flow, your rate outlook and your remaining tenure. Most banks show you only the new EMI. FinPick shows you the total interest saved or paid over the life of the loan, so you can pick the option that fits your goal.
If you are facing a reset, or if you have an old MCLR loan and you are wondering whether to migrate, book a FinPick call. Bring your latest loan statement (showing outstanding balance, current rate and remaining tenure). We will model raise-EMI versus extend-tenure versus switch-to-fixed versus prepay using your actual numbers, show you the five-year and full-tenure cost of each option, and help you decide which one saves the most money or frees the most cash flow. One conversation, and you will know exactly what to do.
Do this today:
- Find your latest home loan statement or log in to your bank app. Note your outstanding balance, current interest rate, EMI, remaining tenure and reset date.
- Check whether your loan is linked to an external benchmark (repo, T-bill) or MCLR. It will say in the statement or sanction letter.
- If your loan is floating-rate and you have a lump sum (bonus, maturity, savings), calculate how much interest you will save by prepaying. From January 2026, it costs nothing.
- If you are facing a reset or a rate change, list your four options (raise EMI, extend tenure, switch to fixed, prepay) and the cost or benefit of each over the remaining tenure.
- Book a FinPick call with your loan statement. We will model all four options with your actual numbers and show you which one fits your cash flow and total-cost goal. WhatsApp “home loan reset” to a FinPick adviser to start.