
You’ve typed “SIP 5000 per month returns” into the search box. You want a number. A promise. Something to plan around.
Here’s what the regulators say first: AMFI states clearly that mutual fund schemes are not guaranteed or assured return products, and that the value of your investment may go up or down. SEBI adds that there are no guaranteed returns, and that past performance does not guarantee future results. Both say you can lose your principal.
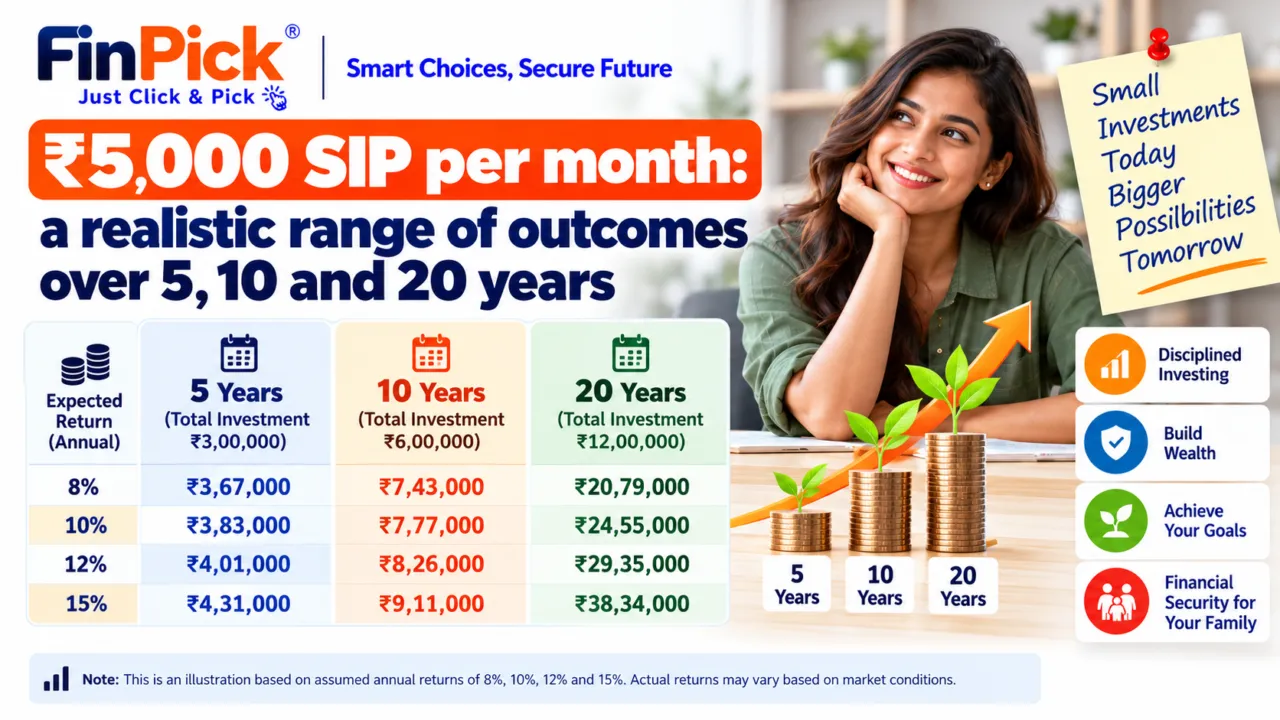
Now let’s look at the arithmetic, the assumptions and what a ₹5,000 monthly SIP could illustrate over 5, 10 and 20 years, keeping those warnings front and centre.
What You’re Actually Investing
The invested amount is pure arithmetic. ₹5,000 a month for 5 years is ₹3,00,000. For 10 years, ₹6,00,000. For 20 years, ₹12,00,000. That part is certain. What happens to that money is not.
Key Facts You Must Know Before You Look at Any Table
- AMFI states mutual fund schemes carry no guarantee or assurance of returns, and the value may go up or down.
- AMFI says past performance does not guarantee future performance, and investment involves risk including possible loss of principal.
- SEBI confirms there are no guaranteed returns, and past performance does not guarantee returns.
- AMFI defines a SIP as investing a fixed amount periodically at fixed intervals, with instalments as low as ₹500 a month.
- AMFI states rupee cost averaging does not assure profit, nor does it protect against losses in declining markets.
- SEBI circular MFD/CIR/4/51/2000 dated 5 June 2000 bars mutual fund advertisements from forecasting NAV growth or promising returns not backed by guarantees.
Why This Topic Matters
₹5,000 SIP is the most searched mutual fund query in India. Yet most content either hypes guaranteed-sounding returns or buries the risk warnings in fine print. You deserve to see the arithmetic, understand the assumptions and know what regulators actually say.
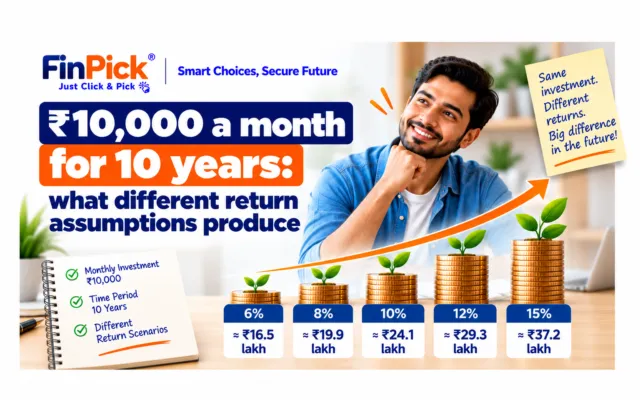
The gap between an assumed 8% and an assumed 12% over 20 years is enormous: ₹29.64 lakh versus ₹49.95 lakh. But neither figure is a forecast. Both are illustrations of what would happen if markets delivered that smooth rate every year, which they never do.
How a SIP Actually Works
AMFI describes it simply: you invest a fixed amount in a mutual fund scheme periodically, at fixed intervals. Each instalment buys units at that day’s NAV. When the NAV is low, you get more units. When it’s high, you get fewer. Over time, this averages your cost per unit.
That’s rupee cost averaging. It’s a mechanism, not a magic trick. AMFI says clearly it does not assure profit, nor does it protect you against investment losses in declining markets.
Your final value depends entirely on the NAV on the day you redeem, multiplied by the total units you’ve accumulated. If the NAV has fallen below your average cost, you lose money.
A Worked Example: ₹5,000 a Month Over Three Time Horizons
These are illustrative calculations at assumed annual rates of 8%, 10% and 12%. They are not forecasts, not promises and not predictions. They show what the arithmetic produces if markets delivered that rate smoothly, which actual markets do not.
The figures below assume the SIP is debited at the start of each month. If debited at month end, values are slightly lower. Actual results depend on the NAV on each instalment date and the NAV on the day you redeem.
5 years (₹3,00,000 invested):
- At assumed 8%: ₹3,69,834 (illustrative gain ₹69,834)
- At assumed 10%: ₹3,90,412 (illustrative gain ₹90,412)
- At assumed 12%: ₹4,12,432 (illustrative gain ₹1,12,432)
10 years (₹6,00,000 invested):
- At assumed 8%: ₹9,20,828 (illustrative gain ₹3,20,828)
- At assumed 10%: ₹10,32,760 (illustrative gain ₹4,32,760)
- At assumed 12%: ₹11,61,695 (illustrative gain ₹5,61,695)
20 years (₹12,00,000 invested):
- At assumed 8%: ₹29,64,736 (illustrative gain ₹17,64,736)
- At assumed 10%: ₹38,28,485 (illustrative gain ₹26,28,485)
- At assumed 12%: ₹49,95,740 (illustrative gain ₹37,95,740)
These figures are before expense ratio, exit load and capital gains tax.
The Goosebumps Moment: Time Matters More Than the Rate
Look at the 10% column. At 10 years, the illustrative value is ₹10,32,760 on ₹6,00,000 invested. At 20 years, it’s ₹38,28,485 on ₹12,00,000 invested. You’ve invested exactly double the money, but the value is nearly four times higher.
That’s compounding at work. The longer you stay, the more your earlier instalments have time to grow. But here’s the catch: this arithmetic assumes the market delivers 10% every single year, which it never does. Actual returns swing wildly. Some years you gain 30%, some years you lose 20%. The final number depends on the sequence and timing of those swings, not on a smooth average.
Who Is Affected
Anyone searching for ₹5,000 SIP returns will find illustrative ranges here, not promises. Current SIP investors need to understand that rupee cost averaging does not assure profit or protect against losses. The wide range between 8% and 12% assumptions over 20 years shows how sensitive outcomes are to actual market performance, which no one can predict.
FinPick Analysis
Most SIP calculators online show you a single number and let you believe it’s what you’ll get. That’s misleading. The regulators are clear: no returns are guaranteed, and you can lose your principal.
What the arithmetic does show is that time is your biggest lever. The difference between 5 years and 20 years at the same assumed rate is far larger than the difference between 8% and 12% over the same period. If you’re starting a SIP, the most important decision is to start and to stay, not to chase the fund with the highest past return.
The second insight: the range of outcomes is wide. At assumed 8% over 20 years, you illustrate ₹29.64 lakh. At assumed 12%, ₹49.95 lakh. That’s a ₹20 lakh difference on the same ₹12 lakh invested. Actual markets will not deliver either of those smooth lines. Your real outcome will depend on which years are good, which are bad and when you redeem.
This is why goal-based planning matters. If you need the money in 5 years for a house down payment, a SIP in equity funds carries real risk of loss. If you’re investing for retirement 20 years away, short-term volatility matters less, but you still need to understand there are no guarantees.
What You Should Know Before You Act
- These figures are illustrations, not forecasts. SEBI’s circular dated 5 June 2000 bars mutual fund advertisements from forecasting NAV growth or promising returns not backed by guarantees.
- Rupee cost averaging is a mechanism, not a profit guarantee. AMFI says it does not assure profit, nor does it protect against losses in declining markets.
- The figures above are before costs and tax. Mutual funds charge an expense ratio (deducted from the NAV daily), and you may pay exit load if you redeem early. Capital gains tax applies when you sell.
- Inflation erodes purchasing power. ₹49 lakh in 20 years will buy less than ₹49 lakh today, though no verified inflation figure is available here to quantify that.
- The difference between start-of-month and end-of-month SIP values in the table depends on when your SIP is actually debited and which NAV is applied. That varies by fund house.
- No mutual fund category or scheme is named here because FinPick does not recommend products in educational content. The right choice depends on your goal, time horizon and risk appetite, which an adviser can map in a conversation.
Frequently Asked Questions
Q: Is 12% return guaranteed in equity mutual funds? A: No. AMFI and SEBI both state clearly that mutual fund schemes carry no guaranteed or assured returns. The 12% figure in the table is an assumed rate used for illustration, not a promise or a forecast.
Q: Can I lose money in a SIP? A: Yes. AMFI states that investment involves risk including possible loss of principal. If the NAV when you redeem is below your average purchase cost, you will lose money.
Q: Does rupee cost averaging guarantee profit? A: No. AMFI says rupee cost averaging does not assure profit, nor does it protect against investment losses in declining markets.
Q: Which is better: 8%, 10% or 12%? A: These are assumed rates for illustration, not choices you can pick. Actual returns depend on market performance, which no one can predict. The table shows that time matters more than the rate.
Q: Are these figures after tax? A: No. The illustrative values are before expense ratio, exit load and capital gains tax. Your actual amount in hand will be lower.
Q: Should I start a ₹5,000 SIP today? A: That depends on your goal, time horizon and risk appetite. The arithmetic shows the mechanism and the range of assumptions. A conversation with an AMFI-registered distributor can map your specific situation and help you decide.
Conclusion
The arithmetic of a ₹5,000 monthly SIP is transparent: ₹3 lakh invested over 5 years, ₹6 lakh over 10, ₹12 lakh over 20. What happens to that money depends entirely on market performance, which carries no guarantee.
The illustrative range at assumed rates of 8% to 12% shows two things clearly: time is your biggest lever, and the range of outcomes is wide. Neither insight tells you what will actually happen, because AMFI and SEBI both confirm that past performance does not predict future results and that you can lose your principal.
What you can do is understand the mechanism, see the assumptions, and make a decision based on your own goal and time horizon, not on a promised number. That’s what financial planning is: arithmetic, honesty and a conversation about what matters to you.
Do This Today
- Write down one financial goal you want this SIP to fund: house down payment, child’s education, retirement, something else.
- Write down when you need the money: 5 years, 10 years, 20 years.
- Check if you can commit ₹5,000 every month without touching it, even if the value falls in the short term.
- Save this article and the illustrative table. Do not treat any row as a promise.
- WhatsApp a FinPick adviser with your goal, your time horizon and one question: “Which mutual fund category suits this?” Bring the goal and the timeline. The adviser will map the risk and the asset mix, not push a product.
FinPick is an AMFI-registered Mutual Fund Distributor (ARN-121216). We structure, we don’t sell. Let’s talk.