
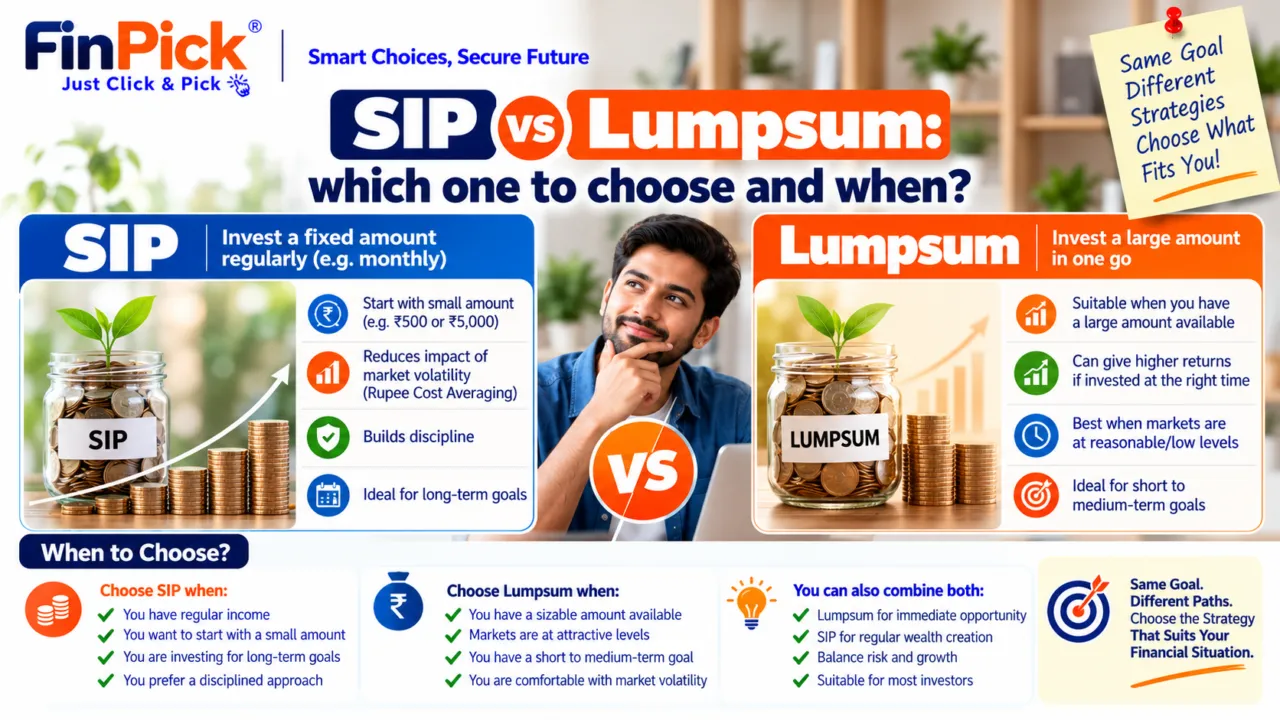
SIP or Lump Sum: Which Way Should You Invest in Mutual Funds?
Your annual bonus just hit your account. ₹3 lakh. You open your banking app, stare at the balance, and wonder: should I invest it all today or spread it over the next two years in monthly chunks? The answer isn’t about which method is safer. It’s about which one fits your cash flow, your horizon and your comfort with market swings.
What a SIP Actually Is (and Isn’t)
A SIP is not a separate product. It is a method of investing in mutual funds by putting in a fixed amount at regular intervals instead of one lump sum. The money still goes into a real mutual fund scheme. You can start a SIP in the same equity fund where someone else invests a lump sum. The scheme, the risk, the portfolio are identical. Only the entry pattern differs.
AMFI states that perfectly timing market highs and lows is impossible. A SIP removes that timing decision by spreading your entry over many dates.
Do this today: Open the website of any mutual fund house and look at one equity scheme. Note the minimum SIP amount (can start from as low as ₹101) and the minimum lump sum amount (mostly ₹500 or more). You will see they are two ways into the same scheme.
How Rupee Cost Averaging Works
When you invest a fixed sum on fixed dates, you buy more units when prices fall and fewer when prices rise. Over time, this lowers the average cost per unit you hold. AMFI calls this rupee cost averaging.
Here is the arithmetic. Suppose you invest ₹10,000 on three dates. The NAV on those dates is ₹100, ₹80 and ₹125.
- First month: ₹10,000 ÷ ₹100 = 100 units
- Second month: ₹10,000 ÷ ₹80 = 125 units
- Third month: ₹10,000 ÷ ₹125 = 80 units
Total: 305 units for ₹30,000. Your average cost per unit is ₹30,000 ÷ 305 = ₹98.36.
The simple average of the three NAVs is (₹100 + ₹80 + ₹125) ÷ 3 = ₹101.67. Your average cost is lower because you bought more units when the NAV was ₹80.
Now suppose you invested the entire ₹30,000 on the first date at NAV ₹100. You would have 300 units at an average cost of ₹100. If the NAV later rose to ₹125, you would be ahead. If it fell to ₹80 and stayed there, you would be down 20%. The lump sum result depends entirely on the NAV path after your entry date. The SIP spreads that risk over time.
This is an illustration using made-up NAVs, not a projection. The mechanism is real, the benefit is conditional. AMFI states that over five years or longer, if the market has gained, the average unit cost tends to be lower than the prevailing NAV. That is arithmetic, not a promise.
Do this today: Pick any equity mutual fund scheme on a fund house website. Download the NAV history for the last six months. Calculate how many units a fixed amount (say ₹5,000 or ₹10,000) would have bought on the first of each month. Add them up and divide your total investment by total units. Compare that average cost to the NAV today. You will see rupee cost averaging in your own numbers.
When a SIP Fits Your Situation
A SIP matches your cash flow if you have regular salary income and no large surplus sitting idle. You invest what you earn each month without waiting to save up a lump sum.
HDFC MF suggests a minimum tenure of 5 to 10 years for SIP style investing. If your goal is two years away, a SIP into equity may not give the averaging benefit time to work. SEBI states equity schemes carry comparatively high risk and past performance does not guarantee future results. A SIP does not eliminate that risk, it spreads your entry.
SIPs can be changed, paused or stopped without penalty (check each scheme’s terms in the offer document). You are not locked in. If your income drops or your goal changes, you can stop the auto-debit and resume later.
Do this today: Open your salary account statement for the last three months. Subtract your fixed expenses and your emergency buffer. The amount left over each month is what you can invest without stress. Write it down. That number is your natural SIP amount.
When a Lump Sum Fits Your Situation
A lump sum gives you full market exposure at once. Entry timing matters more because you invest the entire amount at one NAV. If the market rises the next day, you benefit fully. If it falls, you face the full drop.
If you have a windfall (bonus, inheritance, property sale proceeds), you can deploy it as a lump sum. Those with a long horizon and high risk appetite can invest a lump sum in equity, but you need the ability to handle short-term volatility. For shorter horizons or lower risk appetite, debt or liquid funds may fit better because NAV swings are smaller.
If you have ₹5 lakh sitting in a savings account earning a low interest rate while you SIP ₹10,000 a month into equity, you are losing the opportunity cost on the ₹5 lakh. A FinPick adviser can help you structure the deployment: part lump sum into debt, part SIP into equity, or a combination that matches your goals.
Do this today: Check your savings account, fixed deposits and any maturity proceeds sitting idle. Write down the total amount and the date by which you will need it. If you will not need it for five years or more, it is a candidate for equity exposure. If you will need it in two years, debt or liquid funds fit better. Bring these numbers to a call with a FinPick adviser.
The One Thing Most Articles Get Wrong
A common misconception is that one method is safer than the other. The research shows both carry the same market risk because the money goes into the same scheme. A SIP spreads your entry over time, which can lower your average cost, but it does not reduce the scheme’s volatility.
The real difference is cash flow and timing. If you have the money now and a long horizon, a lump sum works. If you earn it month by month, a SIP works. If you have a lump sum but are unsure about equity market levels, you can combine both: invest part now and SIP the rest over 12 or 24 months. Some investors use a Systematic Transfer Plan (STP) for this, but that is outside the scope of this article. Ask a FinPick adviser about it if you want to explore that approach.
AMFI states that perfectly timing market highs and lows is impossible. Rupee cost averaging does not beat the market, it removes the timing decision. That is the insight.
Do this today: Ask yourself one question: do I have the full amount I want to invest sitting in my account right now, or will I earn it month by month over the next year? Your honest answer tells you which method fits.
What the Research Does Not Tell Us (and What to Do About It)
The research brief does not include historical SIP versus lump sum return comparisons across specific market cycles, tax treatment of gains, exit load rules, or current SIP inflow figures. Those details matter.
For tax treatment, check the scheme’s offer document or ask the fund house in writing. For exit loads, read the scheme information document on the fund house website. For historical comparisons, a FinPick adviser can show you the numbers for the specific schemes you are considering.
Do not invest based on what you do not know. If the mechanism makes sense but the details are unclear, bring your questions to a FinPick adviser before you commit.
Do this today: Write down three questions you still have after reading this article. Message a FinPick adviser on WhatsApp with those questions and your monthly surplus or lump sum amount. The adviser will answer them with facts from the scheme documents and regulator guidance, not with generic advice.
What to Do Next
You now know that a SIP is a method, not a product. You know how rupee cost averaging lowers your average entry cost over time. You know that neither method is universally better and the right choice depends on your cash flow, your horizon and your comfort with market swings.
Here is what you can finish today:
- Open your last three months’ bank statements and calculate your average monthly surplus after fixed expenses and emergency buffer.
- List one financial goal you want to reach in five to ten years and estimate the amount you will need.
- Check your savings account, fixed deposits and any maturity proceeds sitting idle right now. Write down the total and the date by which you will need it.
- Decide whether you want to invest that lump sum now, SIP it over time, or combine both.
- Message a FinPick adviser on WhatsApp with one number: your monthly surplus or your lump sum amount. Bring your goal, your horizon and any existing investments to the call. The adviser will help you choose the right schemes, set the right SIP amount and structure the deployment so it matches your cash flow.
Start with what you have, not with what you wish you had. The method will follow.