Motor Insurance
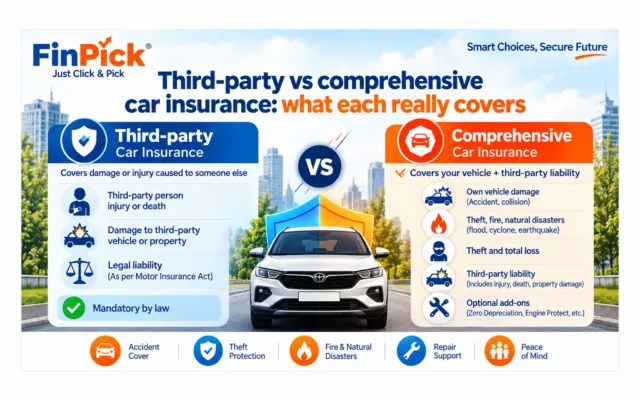
Third-party vs comprehensive car insurance: what each really covers
The law says you must buy third-party cover, but it won't pay a rupee if your own car is stolen or smashed.
Mutual funds, insurance and loans explained plainly, in Marathi, Hindi and English.
The law says you must buy third-party cover, but it won't pay a rupee if your own car is stolen or smashed.
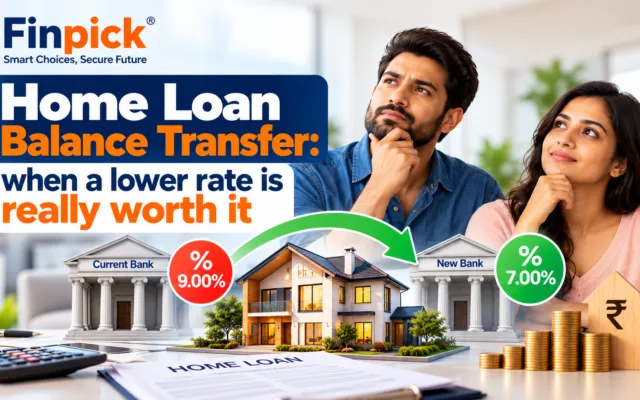
From 1 January 2026, no pre-payment penalty on floating-rate home loans, but does the math actually work for you?
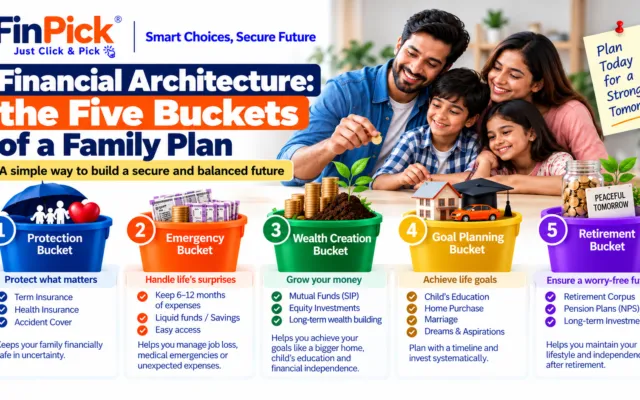
Protection, emergency fund, goals, retirement and tax: here's how to map your money so nothing falls through the cracks.
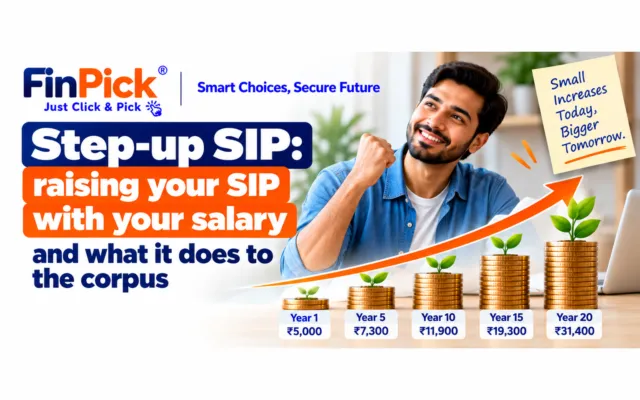
A step-up SIP lets you increase your instalment every year without starting fresh, here's the arithmetic and what to fill in the form.
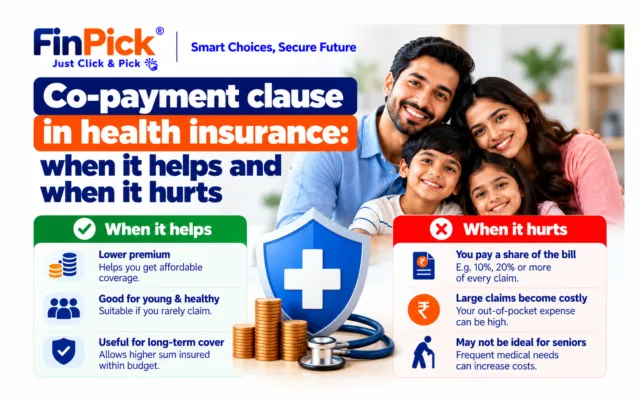
A 20% co-pay can cut your premium by ₹6,000 a year, but one large claim could wipe out sixteen years of that saving.
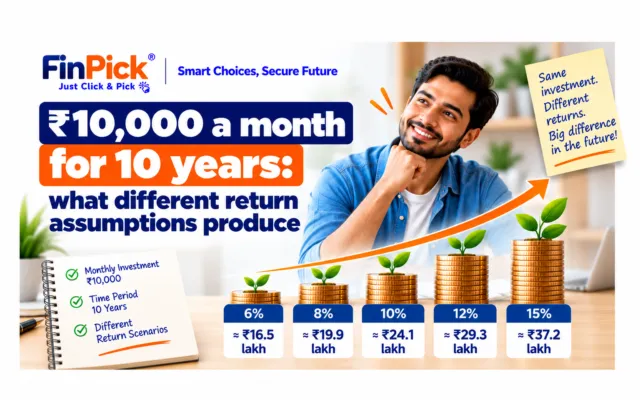
The same ₹12 lakh invested can illustrate maturity values from ₹16.5 lakh to ₹23.2 lakh, depending on the rate you assume.
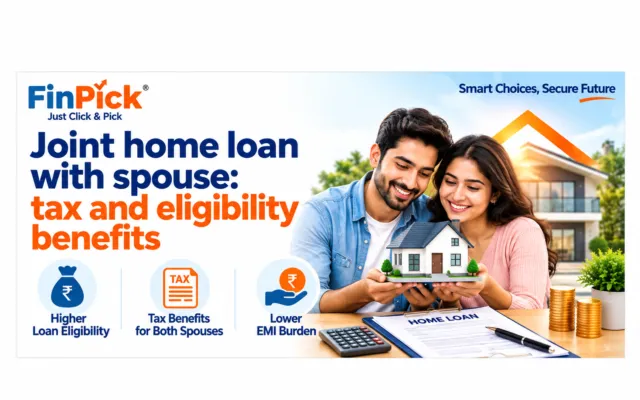
Clubbing incomes raises your loan eligibility, and under the old tax regime each co-owner can claim separate deductions on interest and principal.
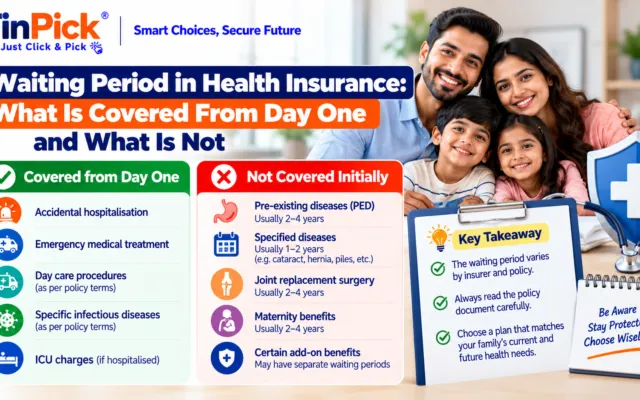
The three types of waiting periods, the five-year moratorium rule, and how portability credits carry over when you switch insurers
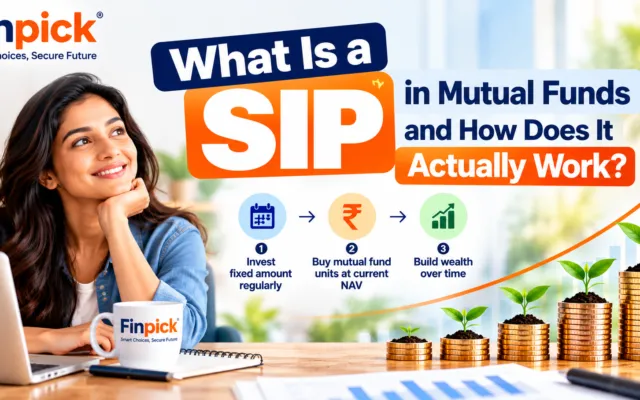
A plain-language guide to systematic investment plans, rupee cost averaging and what SEBI's own numbers show.
IRDAI does not prescribe an income multiple, your cover depends on your dependants, debts, goals and affordability, calculated step by step.