
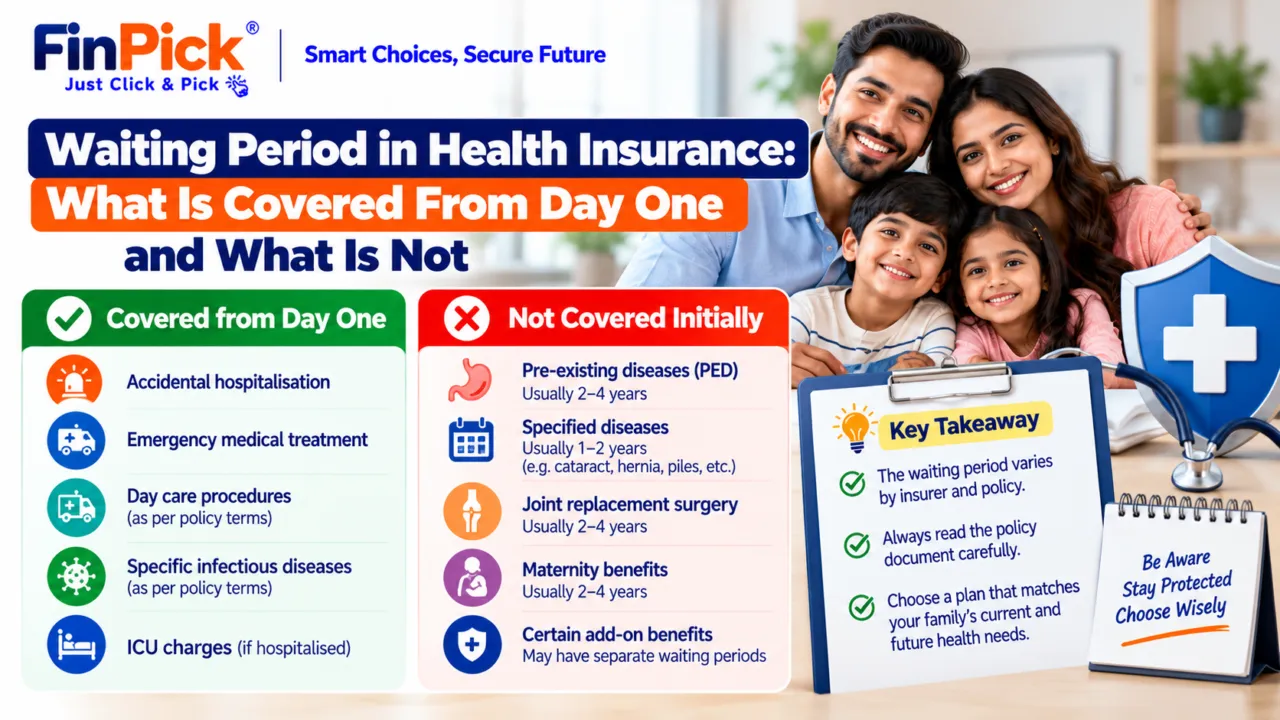
You buy a health policy in January. In March, you need surgery for a hernia. The insurer rejects the claim. Why? Because hernia fell inside a specific-disease waiting period you did not know existed.
Waiting periods are the time windows during which certain treatments are not covered, even though you are paying premiums. They exist to prevent people from buying insurance only when they know they need a claim. But the rules changed in April 2024, and most buyers still do not know what is covered from day one, what is not, and how the clock resets (or does not reset) when you switch insurers.
Here is what you need to know before you buy or renew.
What Happened
From 1 April 2024, the Insurance Regulatory and Development Authority of India (IRDAI) capped the maximum waiting period for pre-existing diseases and specific diseases at 36 months of continuous coverage, down from 48 months. On 29 May 2024, IRDAI issued the Master Circular on Health Insurance Business, which laid out the moratorium rule: after 60 months of continuous coverage, no health claim can be contested for non-disclosure or misrepresentation, except in cases of proven fraud. The circular also confirmed that when you port or migrate to a new insurer, you carry over your waiting-period credits, no-claim bonus and moratorium credit, so you do not start from zero.
Key Facts
- Three types of waiting periods: initial (typically 30 days, except for accidents), specific diseases (for named conditions like cataract or hernia, capped at 36 months), and pre-existing diseases (capped at 36 months of continuous coverage).
- Moratorium after 60 months: After five years of continuous coverage, no claim can be contested for non-disclosure, except established fraud (IRDAI Master Circular, 29 May 2024, Chapter I clause 13).
- Portability carries credit: When you switch insurers, you carry over sum insured, no-claim bonus, specific waiting periods, PED waiting-period credit and moratorium credit (IRDAI Master Circular, portability clause).
- Enhanced sum insured: When you add a new sum-insured portion, waiting periods start afresh only for that enhanced portion (IRDAI Customer Information Sheet template).
- Free look period: 30 days from receipt of the policy document, for policies of one year or more (IRDAI Master Circular, clause 5).
- Caps came into effect: The 36-month caps on PED and specific-disease waiting periods came into effect on 1 April 2024 under the IRDAI (Insurance Products) Regulations, 2024 (cited in news reports; gazette text not verified).
Why It Matters
Most people assume that once they pay the first premium, everything is covered. It is not. A 30-year-old buys a policy in June, develops appendicitis in July, and the claim is paid because accidents and emergencies are covered from day one. But if the same person needs cataract surgery in August, the claim is rejected because cataract falls inside a specific-disease waiting period of, say, 24 months.
The confusion multiplies when you switch insurers. Many buyers think portability means starting from zero, so they stay locked into a policy they dislike. They do not realise that the new insurer must credit the waiting periods you have already served.
How It Actually Works
Health insurance waiting periods come in three layers:
1. Initial waiting period (typically 30 days) Most policies do not cover any hospitalisation in the first 30 days, except for accidents. If you slip and fracture your arm on day 10, it is covered. If you are hospitalised for dengue on day 20, it is not. On continuous renewal, the initial waiting period does not apply again.
2. Specific-disease waiting period (up to 36 months) Certain named conditions, such as cataract, hernia, joint replacement, sinusitis and benign prostatic hypertrophy, are excluded for a stated period, capped at 36 months. The list varies by insurer. Accident-related claims for these conditions are covered from day one.
3. Pre-existing disease (PED) waiting period (up to 36 months) A pre-existing disease is any condition diagnosed, or for which advice or treatment was given, within 36 months before the policy start date. Diabetes, hypertension, thyroid disorders and asthma are common examples. These are covered only after 36 months of continuous coverage (reduced from 48 months in April 2024).
The moratorium (after 60 months) After five years of continuous coverage, the insurer cannot reject a claim on the grounds that you did not disclose a pre-existing condition, unless the insurer can prove fraud. The moratorium clock runs from your first policy for the original sum insured. If you raise the sum insured, the moratorium for the enhanced portion runs for five years from the date of enhancement. Permanent exclusions (for example, cosmetic surgery or congenital conditions, if stated in the policy) remain valid even after the moratorium.
Portability and migration When you port to a new insurer, you carry over your sum insured, no-claim bonus, the waiting periods you have already served, and your moratorium credit. If you have held a policy for 40 months and you port, the new insurer must credit those 40 months. You do not restart the 36-month PED clock or the 60-month moratorium clock. When you add a higher sum insured, waiting periods apply afresh only to the enhanced portion.
Who Is Affected
New buyers: If you buy a policy today, accidents and emergencies are covered from day one. Everything else waits 30 days. Specific diseases wait up to 36 months. Pre-existing diseases wait up to 36 months. After five years, the moratorium kicks in.
Existing policyholders: If you bought your policy before April 2024 and your PED waiting period was 48 months, the new 36-month cap applies from 1 April 2024. Check your policy wording and the Customer Information Sheet to confirm.
People considering portability: If you have held a policy for three years and you are unhappy with the insurer, you can port and carry over your waiting-period credits. You do not lose the time you have already served.
Business owners: Group health policies for employees follow the same waiting-period rules. New joiners serve the waiting periods from their joining date. Existing employees who move from the group policy to an individual policy can carry over credits if the insurer allows migration.
A Worked Example
Scenario: Priya, 35, buys a health policy on 1 January 2024 with a sum insured of ₹5 lakh. She has mild hypertension, diagnosed in March 2022 (within the 36-month look-back period), so it is a pre-existing disease.
- Day 10 (10 January 2024): Priya has a road accident and fractures her wrist. Covered, because accidents are covered from day one.
- Day 20 (20 January 2024): Priya is hospitalised for viral fever. Not covered, because she is inside the 30-day initial waiting period.
- 15 March 2024: Priya needs cataract surgery. Not covered, because cataract is a specific disease with a 24-month waiting period (insurer-specific; the cap is 36 months).
- 1 February 2027 (37 months later): Priya is hospitalised for hypertension-related complications. Covered, because the PED waiting period of 36 months has ended.
- 1 January 2029 (60 months later): The moratorium applies. From this date, no claim can be contested for non-disclosure, except fraud.
- 1 July 2029: Priya ports to a new insurer and raises her sum insured to ₹10 lakh. The new insurer credits her 66 months of continuous coverage (from 1 January 2024 to 1 July 2029). The ₹5 lakh base is past the moratorium. The ₹5 lakh enhanced portion starts a new 60-month moratorium clock and new waiting periods, but only for that ₹5 lakh.
This is an illustration, not a projection. Actual waiting periods and coverage depend on the policy wording and the Customer Information Sheet your insurer provides.
FinPick Analysis
The 36-month cap and the moratorium rule are significant wins for buyers, but they are not automatic. You still need to read the Customer Information Sheet (CIS) to know what your policy actually imposes. The regulation sets the ceiling; your insurer may offer shorter waiting periods, or longer ones up to the cap.
The portability credit is the part most buyers miss. If you have held a policy for three years and your PED waiting period has ended, you can switch insurers without losing that credit. The new insurer must honour it. This breaks the lock-in that used to keep people in bad policies.
One gap remains: the list of specific diseases is not standardised. One insurer may exclude hernia for 24 months, another for 36 months, and a third may not exclude it at all. You cannot compare policies without reading the fine print.
The moratorium is powerful, but it does not erase permanent exclusions. If your policy permanently excludes, say, obesity-related surgery, that exclusion survives the moratorium. And if you raise your sum insured, the moratorium for the enhanced portion starts fresh. So if you plan to increase cover, do it early, not in year four.
What You Should Know Before You Act
Read the Customer Information Sheet (CIS): Every policy must come with a CIS that lists the initial waiting period, the specific diseases and their waiting periods, and the PED waiting period. Do not rely on the brochure.
Disclose everything: The moratorium protects you after five years, but only if you did not commit fraud. Non-disclosure of a known condition can still be contested if the insurer can prove you knew and hid it.
Accidents are covered from day one: If you or a family member has an accident, the claim is payable immediately, even inside waiting periods.
Portability is not a reset: When you port, you carry over waiting-period credits and moratorium credits. Ask the new insurer for a written confirmation of the credits before you port.
Enhanced sum insured restarts the clock, but only for the enhanced portion: If you raise cover from ₹5 lakh to ₹10 lakh, the new ₹5 lakh starts fresh waiting periods. The original ₹5 lakh keeps its credits.
The 36-month cap is a maximum: Your insurer may offer shorter waiting periods. Some policies cover specific diseases after 12 or 24 months. Compare.
Buy-down add-ons may exist: Some insurers offer riders or add-ons to shorten PED or specific-disease waiting periods, usually at extra cost. Check if your insurer offers this and whether it is worth the price.
Frequently Asked Questions
Q: If I port to a new insurer after two years, do I start the PED waiting period from zero? A: No. The new insurer must credit the two years you have already served. You will complete the remaining waiting period (up to 36 months total) with the new insurer. Ask for written confirmation of the credit before you port.
Q: Are maternity expenses subject to waiting periods? A: Yes, if your policy covers maternity. Maternity waiting periods are separate and are not covered in this article. Check your policy wording for maternity-specific clauses.
Q: Can the insurer reject a claim after the five-year moratorium? A: Only if the insurer can prove fraud. Non-disclosure or misrepresentation cannot be used as grounds for rejection after 60 months of continuous coverage, except established fraud.
Q: What counts as continuous coverage for the moratorium? A: Continuous coverage means you have held one or more health policies without a break in coverage. If you port or migrate, the credit carries over. If you let a policy lapse and then buy a new one, the clock resets.
Q: If I have a pre-existing disease, should I wait 36 months before making any claim? A: No. You can claim for accidents, emergencies and non-PED conditions from day one (after the initial 30-day period). Only claims related to the pre-existing disease are excluded for 36 months.
Q: How do I find out which specific diseases my policy excludes? A: The Customer Information Sheet and the policy wording list the specific diseases and their waiting periods. If the insurer has not provided the CIS, ask for it before you buy.
Conclusion
Waiting periods are not traps if you know the rules. Accidents and emergencies are covered from day one. Everything else waits 30 days. Specific diseases wait up to 36 months. Pre-existing diseases wait up to 36 months. After five years, the moratorium protects you from non-disclosure contests, except fraud.
The real power is in portability: you do not lose the time you have already served when you switch insurers. If you have held a policy for three years, your PED waiting period is over, and you can port without restarting the clock. Most buyers do not know this, so they stay locked in.
Read the Customer Information Sheet. Compare the specific-disease lists. Disclose everything. And if you are not sure whether your waiting periods have ended or how portability credits work, bring your policy documents to a conversation with a FinPick adviser. We will show you the arithmetic and help you decide whether to stay, port or upgrade.
Do this today:
- Find your Customer Information Sheet (it came with your policy document). If you do not have it, email or call your insurer and ask for it.
- List the three waiting periods your policy imposes: initial (usually 30 days), specific diseases (with the list and the months), and PED (up to 36 months).
- Calculate how many months of continuous coverage you have served since your first health policy (count portability credits if you switched insurers).
- Check whether you are past the moratorium (60 months). If you are, note that your claims cannot be contested for non-disclosure, except fraud.
- If you are considering portability, WhatsApp a FinPick adviser with your current policy name, sum insured, and months of coverage. We will confirm your portability credits and compare options.
Bring your policy wording, the Customer Information Sheet, and your premium receipt to a call with a FinPick adviser. We will walk you through what is covered, what is not, and whether portability makes sense for you.